Financial independence in your twenties does not have to mean retiring early or reaching one impressive account balance. A practical first definition is having enough control over your cash flow that bills are covered, a manageable surprise does not overturn the month, and money gives you more choices instead of fewer. You can build that kind of independence one decision at a time. A strong first safeguard is an emergency fund that protects the rest of your plan from ordinary financial shocks.
Define what independence means right now
A goal becomes useful when you can tell whether you are moving toward it. Your first version of financial independence might mean paying recurring bills without borrowing, moving into your own place, leaving an unhealthy job without immediate panic, or helping family without missing your own obligations.
Choose one near-term outcome and give it a date. Then identify the monthly habits that support it. This keeps the plan focused on your actual life instead of comparing your progress with someone else’s income, home, or social-media highlight reel.
Step 1: Build a clear cash-flow picture
Start with what already happened, not what you hope happened. Review recent checking, credit-card, and payment-app activity. List take-home income, fixed bills, flexible spending, debt payments, and less frequent costs. The CFPB recommends looking back over several months so costs such as insurance, medical expenses, tuition, family support, and seasonal spending are not overlooked.
Compare total income with total spending. If your budget says money should remain but the account balance does not, look again for irregular purchases, fees, subscriptions, or timing problems. The budget calculator can help organize the numbers into a monthly view.
| Category | What to review |
|---|---|
| Fixed bills | Rent, utilities, insurance, minimum debt payments |
| Flexible spending | Food, transportation, entertainment, subscriptions |
| Irregular costs | Repairs, medical expenses, annual fees, family support |
Make the plan fit payday timing
A monthly total can look balanced while one particular week still runs short. Map each bill to its due date and compare those dates with incoming pay. When possible, ask a creditor or service provider whether a different due date is available. The goal is not a perfect spreadsheet; it is a cash-flow plan you can follow without repeated late fees or emergency borrowing.
Step 2: Create an emergency reserve in stages
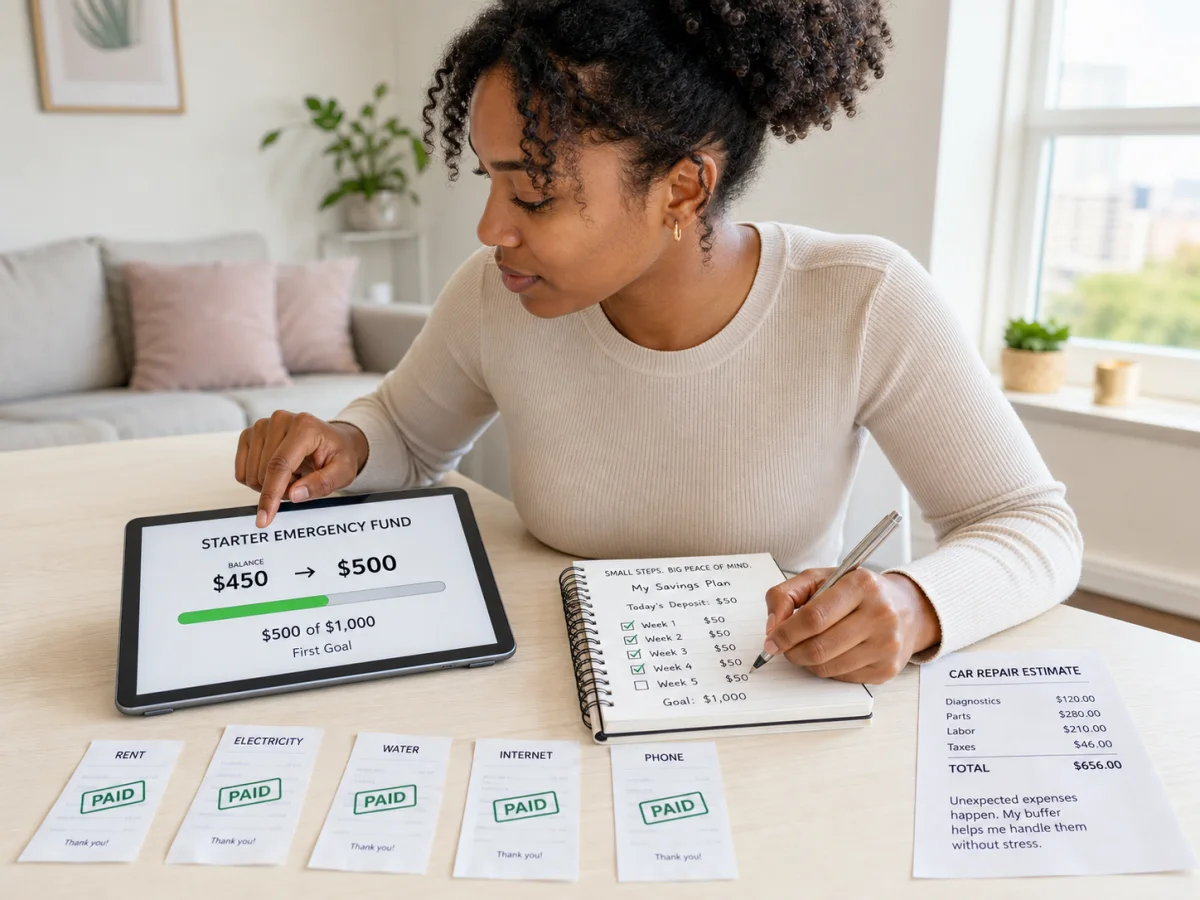
A reserve gives the rest of the plan room to work. Start with a first-line amount for one common disruption, then build toward one month of essential expenses. After that, decide whether income variability, dependents, health needs, transportation, or limited backup support call for a larger cushion.
Keep the reserve safe, accessible, and separate from routine spending. Do not invest money needed for near-term bills or an emergency reserve. For a full calculation process, use Emergency Fund 101.
Step 3: Manage debt deliberately
Make a debt list with the lender, balance, interest rate, minimum payment, due date, and any important terms. Pay required minimums on time when you can. If you have extra money available, choose a payoff method you understand and can sustain.
- Highest-interest-rate method: Direct extra money to the debt with the highest rate first. CFPB guidance notes that this approach addresses the costliest debt first and can save money over time.
- Smallest-balance method: Direct extra money to the smallest debt first. This may produce a faster visible win, though the CFPB notes that it can cost more overall when higher-rate debt remains.
Neither method fixes a budget that is consistently short. If minimum payments are unmanageable, contact the lender or a qualified nonprofit credit counselor before skipping bills or accepting a consolidation offer you do not understand. Compare rates, fees, repayment length, and total cost rather than focusing only on a lower monthly payment.
Step 4: Automate the priorities you can afford
Once required bills are covered, arrange a recurring transfer to the next goal. It could go to emergency savings, a known upcoming expense, or a retirement account. Start at a level that does not force you to reverse the transfer later. Review the amount after a raise, job change, rent change, or debt payoff.
Separate accounts or labeled savings categories can make tradeoffs visible. A car-repair category, moving category, and emergency reserve each have different jobs. When every dollar of savings sits in one pile, it is easier to spend money intended for a more important goal.
Step 5: Learn before you invest
Investing is generally for goals far enough away to withstand market changes. Investor.gov identifies time horizon and risk tolerance as central to investment decisions and describes diversification as spreading money among investments to reduce risk. Diversification cannot prevent every loss, and a fund is not automatically diversified just because it owns multiple holdings.
If an employer offers a retirement plan, read the enrollment rules, vesting terms, investment choices, fees, and any matching formula. A match is not available in every plan and may come with conditions. Investor.gov also warns that fees and expenses can materially affect results over time, so compare total costs rather than assuming the default option is best.
Avoid investments you cannot explain. Be skeptical of guaranteed returns, pressure to act immediately, and anyone who discourages questions. For an individualized recommendation involving investments, taxes, or retirement accounts, consult an appropriately qualified professional who can review your complete situation.
Step 6: Protect the progress you make
Financial independence is also about reducing avoidable setbacks. Review insurance needs, beneficiaries, account alerts, password security, credit reports, and recurring subscriptions. Store recovery information securely and know how to contact financial institutions if an account or device is compromised.
Protection also includes leaving room for ordinary life. A plan that allows no flexible spending may be difficult to maintain. Decide what matters, fund those priorities honestly, and cut expenses that deliver little value instead of treating every enjoyable purchase as a mistake.
A practical 30-day plan
- Week 1: Review transactions and build an accurate cash-flow picture.
- Week 2: Choose an emergency-savings milestone and automate one sustainable transfer.
- Week 3: Complete the debt list and select a payoff method.
- Week 4: Review workplace benefits, account security, fees, and the next monthly goal.
Continue with the guided Money page, use the verified Budget Calculator for your numbers, or browse the current Money resources. Progress comes from a plan you can repeat, not one dramatic month.
Frequently asked questions
How much should I save first?
Choose a first milestone that covers one realistic disruption, then build toward a larger reserve based on your essential expenses and personal risks.
Should I pay debt or save?
Required payments come first. After that, the balance between extra debt payments and savings depends on interest rates, cash-flow stability, and how exposed you are to emergencies.
When should I start investing?
Investing usually makes more sense for longer-term goals after near-term bills and emergency needs are protected. Learn the risks, fees, and account rules before committing money.